A free LBO model template in Excel, with a complete worked deal
Sources and uses, a two-tranche debt schedule, taxes, the three statements, covenants, exit and sponsor returns: twelve linked sheets, one fictional deal, no macros.
The file models one leveraged buyout from signing to exit. A sponsor buys Kestrel for $450 million, 9.0 times $50 million of EBITDA, with a $225 million first-lien term loan, a $50 million second lien and $200 million of equity. Five years later it earns 17.05% on its money and 2.20 times what it put in. Every one of those numbers is a formula you can move.
Get the template
One Excel file, no macros, nothing locked. Free: enter your email address and the download opens at once, along with the other 129 free models.
Kestrel_LBO_Model.xlsx (95 KB) · a copy for Google Sheets
You join the reader list: one email when a new free model or a new book comes out, and a few notes on using the models. Leave in one click. Already on the list? Enter the same address. How your address is used.
Need the full deal structure? The LBO Model, Pro Edition adds four debt tranches, covenants, a management ratchet and 31 checks, with no circular reference and no macros. $99 → · Watch the 60-second preview · Learn to build it: video course
The book behind this model
This file is one worked case from The Buyout Investor. The book explains every assumption, every sheet and the decision the numbers support, chapter by chapter.
Get the book on Amazon → Or the DRM-free PDF edition, $19.99
Also on Amazon UK · Amazon Germany · Amazon France · Amazon Canada.
Want every model at once?
The Financial Model Library: all 130 models from this site in one download, organised by theme, plus two modelling books in DRM-free PDF (Financial Modeling from First Principles and Real Estate Financial Modeling).
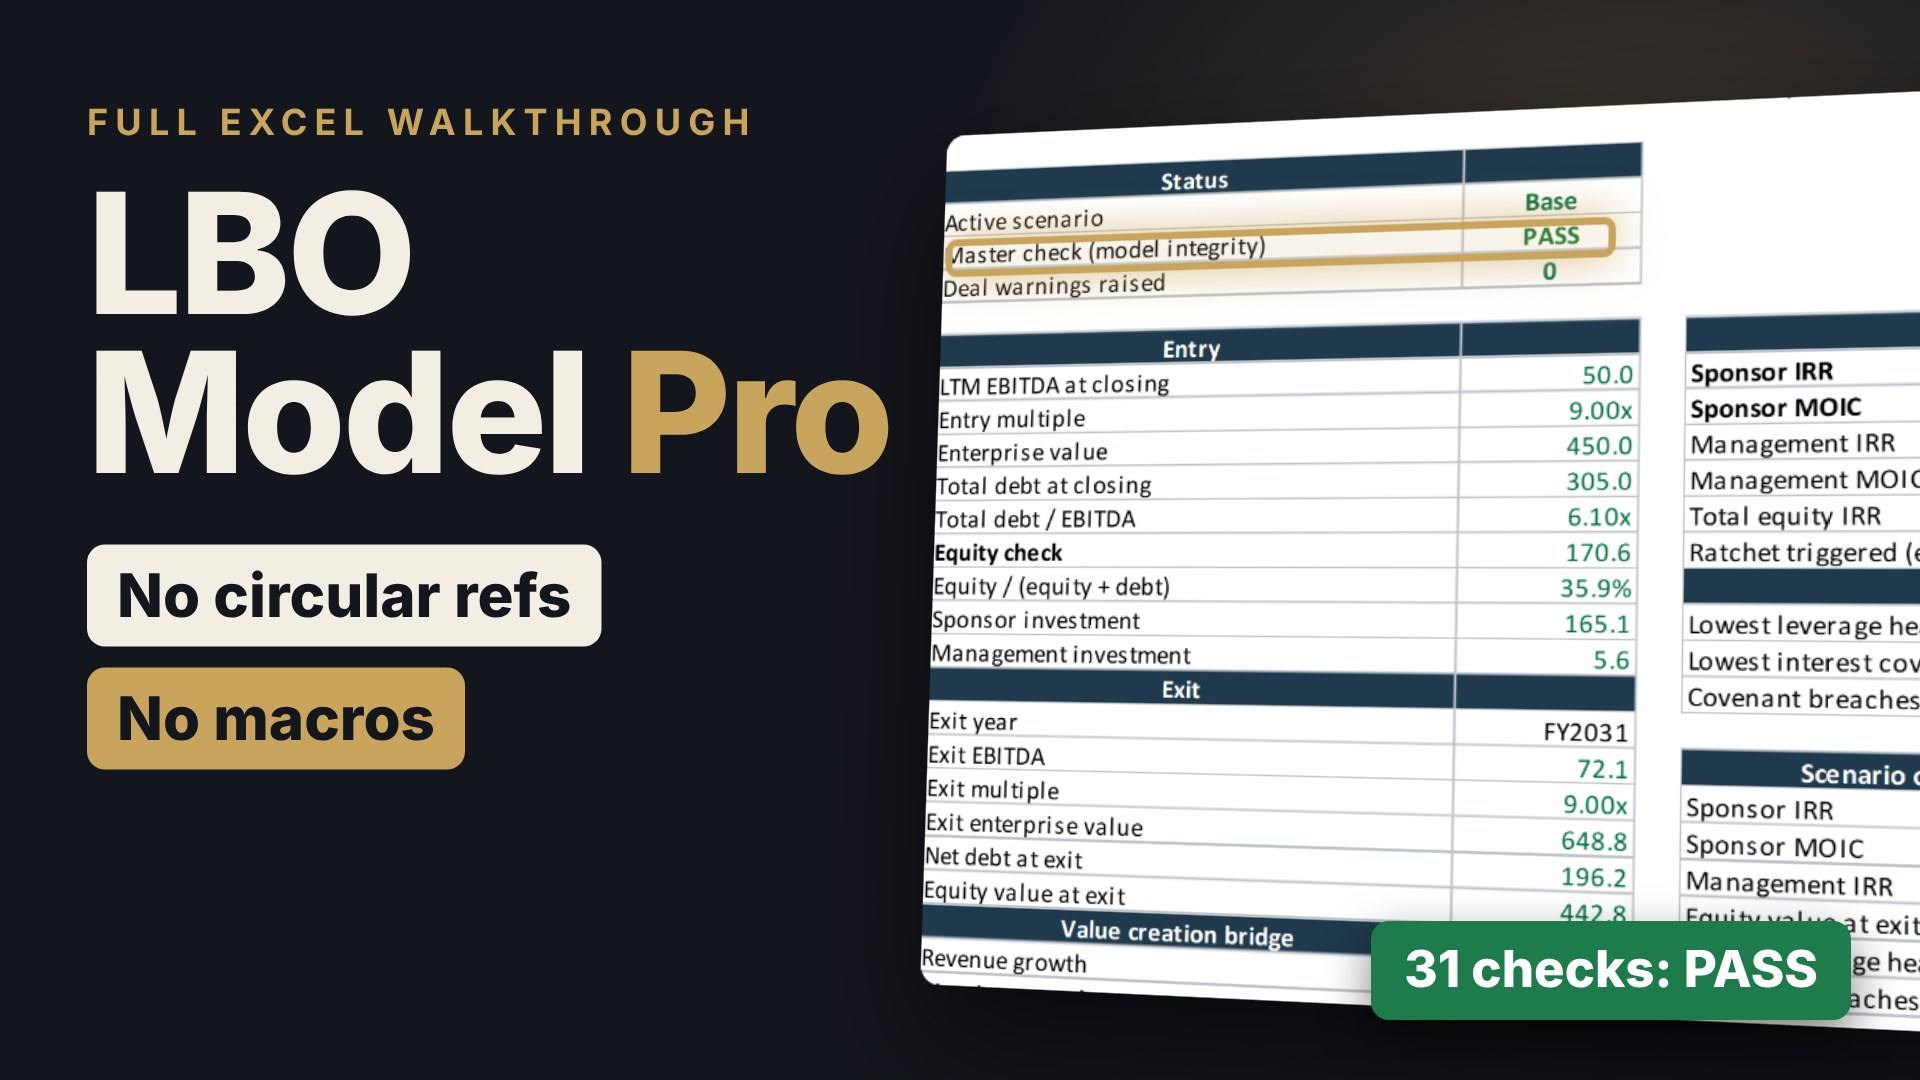
LBO Model, Pro Edition: seven-year buyout model with four debt tranches, covenants, a management ratchet, 31 checks, a blank copy and an 18-page guide. $99 → · See what is inside · Watch the 5-minute demo
The Pro Models Bundle: LBO, Development and Fund models, Pro Editions. $199 instead of $327 → · See what is inside
This free file stays free. Secure checkout by Stripe.
Not on Amazon: 19 paperbacks by Julian R. Sterling on markets, funds and compliance, printed on demand and shipped worldwide. Browse the bookshop →
What is in the file
Twelve sheets, in the order the calculation runs. Inputs are blue type on a yellow fill and sit on one sheet; everything else is a formula.
- Assumptions
- Every input in one place: price, fees, the two debt tranches and their pricing, the operating plan, the holding period.
- Sources_Uses
- The price, the refinancing of existing debt, both kinds of fees, the cash left on the balance sheet, and the equity as the balancing item. A line that must read zero proves sources equal uses.
- Operating
- Revenue to EBITDA year by year.
- Debt
- Both tranches and the revolver: interest on opening balances, mandatory amortisation, a cash sweep that steps down with net leverage, and a revolver drawn only to hold minimum cash.
- Tax
- Cash taxes after interest, so the tax shield of the debt is in the numbers rather than assumed.
- Cash_Flow and Balance_Sheet
- Free cash flow and a balance sheet that balances every year.
- Covenants
- Leverage and coverage tested against their levels, with the headroom shown.
- Exit
- Exit value, net debt at exit and the equity bridge.
- Returns
- Sponsor flows by year, IRR on annual flows and by XIRR on dated flows, the multiple, and where the gain came from.
- Checks
- Every figure the book prints set against what the model computes, with a verdict on each line.
What the worked deal returns
| Measure | Value |
|---|---|
| Enterprise value at entry | $450m (9.0x EBITDA) |
| Total debt at closing | $275m (5.5x EBITDA) |
| Sponsor equity | $190m |
| Sponsor IRR, annual flows | 17.05% |
| Sponsor IRR, XIRR on dates | 17.04% |
| Sponsor multiple of money | 2.20x |
| Cumulative free cash flow over the hold | $88.1m |
| Cumulative cash interest | $126.5m |
| Net debt paid down | $35.3m |
| EBITDA growth, compounded | 9.25% |
Read the last lines together. Over the hold the company pays $126.5 million of interest and $38.7 million of tax, and still repays $35.3 million of net debt. But the gain in enterprise value is 55.6% of the entry price: most of the return comes from EBITDA growth, not from paying down debt. That is the split an investment committee should ask for, and the Returns sheet prints it.
How to use it on your own deal
- Open Assumptions and overwrite the blue cells: EBITDA, entry multiple, fees, the tranche sizes and pricing, the plan.
- Look at Sources_Uses first. If the check line is not zero, an input is inconsistent.
- Read Covenants before Returns. A deal that breaks its leverage test in year two has no return worth reading.
- Change the holding period on Assumptions: Exit and Returns follow it.
- Keep the Checks sheet: once you change inputs it stops matching the book, which is expected. Use its structure for your own tie-outs.
Questions people ask about it
Is this LBO model really free?
Yes. It is a companion file to a book. The file costs nothing. You enter an email address, the download opens at once, and you can leave the reader list in one click.
Does it use macros or circular references?
No macros and no circular reference: interest is charged on opening balances, which the model already knows at the start of each year. The file recalculates in Excel, LibreOffice or Google Sheets without iterative calculation.
Why two different IRRs?
Annual flows put every cash flow on a year end. XIRR uses the actual dates. On this deal they give 17.05% and 17.04%; on a deal with interim dividends the gap can matter.
Can I use it for a real transaction?
You can reuse the structure. The deal, the company and every figure in it are fictional, and nothing here is investment advice.
The rest of the files
This template is one of the companion files for The Buyout Investor: the full set adds the deal-to-fund bridge, the returns and sensitivities workbook and the 60-minute test. Free, like this one.
Worked questions from the same book
Short articles that each answer one question with the arithmetic shown, on the same ground as this model.
- How do you build a sources and uses table for an LBO?
- How does a dividend recap affect IRR and MOIC?
- How do you convert MOIC to IRR?The exact grid by holding period, the logarithm shortcut for doing it in your head, and why the same 2.20x can be 17.1 or 23.9 per cent.
- Does holdco PIK debt raise an LBO's equity IRR?A holdco PIK note cuts the equity cheque and compounds quietly to exit. Whether it helps the sponsor comes down to one comparison.
- What entry multiple can an LBO pay and still make a 20% IRR?
- When should a buyout fund sell? IRR vs MOIC by year of exit
Other free templates
- Real estate property modelRent roll, cash flow, debt and returns for one asset, empty and ready to fill.
- Residual land valuationDevelopment appraisal with the four downside tests and peak debt.
- DCF with terminal valuePerpetuity growth and exit multiple side by side, with the TV share of value.
- Distribution waterfall modelReturn of capital, pref, catch-up and carry, three catch-up readings, European vs deal-by-deal.
- Loan sizing: LTV, LTC, DSCR, debt yieldThe four lender tests at once, the binding one, and a rate shock.
- Direct lending credit modelUnitranche underwriting: coverage, leverage, sweep, base, downside and stress.
- Data center financial modelTurnkey, powered shell and powered land on one campus, levered returns and delay.
- 13-week cash flow modelLiquidity on paper against usable liquidity, a springing covenant and six levers.
- Small business acquisition model (SBA loan)SBA 7(a) loan sized in closed form, lender coverage against cash coverage, exit returns.
- 3-statement financial modelFive-year forecast feeding a DCF and an LBO on one case, with a blank build.
- Project finance modelSolar and storage project, debt sculpted to a 1.35x DSCR, no circularity.
- REIT valuation modelFFO, AFFO, NAV and the implied cap rate for one REIT, plus an empty template.
- Self-storage financial modelCohort rent roll, break-even occupancy, ten-year hold and the bid for one store.
- Tax lien certificate yield calculatorBid, minimum charge and redemption month turned into a real annual yield.
- Sale and leaseback modelNine buildings, the price split five ways, rent cover on the entity that signs.
- PME calculatorKaplan-Schoar PME, PME+, Direct Alpha, IRR and TVPI on one fund's cash flows.
- Working capital peg modelFive peg definitions, the completion-date effect, locked box against completion accounts.
- JV waterfall and promote modelSponsor against capital partner: pref, IRR hurdles and the promote in a two-party JV.
- Student housing modelA 520-bed scheme from rate card to RevPAB, costs, capex cycle and exit value.
- Net effective rent calculatorHeadline rent to net effective rent after rent-free and incentives, and back again.
- VaR and expected shortfall modelParametric VaR and expected shortfall step by step, crisis correlations and a backtest.
- Corporate liquidity modelMinimum liquidity, revolver headroom and the covenant test that takes the revolver away.
- Co-investment fee savings modelWhat an LP co-investment programme saves in fees, its break-even loss rate and deal count.
- Accretion and dilution modelOne deal, four EPS conventions, the twelve-line year-one bridge and the eight charges.
- Budget vs actual variance analysisBudget vs actual variance analysis: one quarter against five comparators, with the spread.
- Cap rate and exit yield calculatorSix entry yields, the one comparable with the exit yield, the sale and the promote.
- Comparable company analysisTrading comps and precedent deals, and the control premium turned into synergies.
- Fulcrum security recovery modelRecovery waterfall that names the fulcrum by arithmetic, across seven enterprise values.
- Price volume mix analysisPrice volume mix analysis: revenue and gross profit bridge, cross term, margin mix and price.
- Private equity fund cash flow modelCapital calls, distributions, J-curve, peak capital at work and the over-commitment ratio.
- LP secondary pricing modelLP interest priced at a discount to NAV: MOIC, IRR, discount against appreciation, stress.
- Subscription line IRR calculatorSame asset with and without a capital call facility: IRR uplift, multiple drag, cost per point.
- Venture capital fund modelFees, carry under five conventions, the J-curve, and gross against net IRR for one fund.
- Commercial real estate underwriting modelValue-add multifamily underwriting, five sensitivities and the maximum bid solved in closed form.
- Real estate DCF modelTen-year office DCF, quarter by quarter and lease by lease: the re-letting cycle priced in full.
- Borrowing base calculatorA borrowing base certificate run live off a 1,880-contract tape, and the advance rate set from stress.
- Debt sculpting modelA toll road's debt sculpted to a 1.25x DSCR, the binding year, the reserve, and the equity return three ways.
- Black-Scholes and binomial option pricingOne option priced three ways (closed form, lattice, simulation) and what eight points of volatility are worth.
- Safety stock calculatorSafety stock at every service level, fill rate solved by bisection, and the three policies priced in euros.
- Mortgage note pricing modelA non-performing note bid from its foreclosure floor, the workout paths, and an eight-loan tape priced loan by loan.
- Forecast bias and accuracy calculatorForecast bias measured against its own noise, the error it removes, and the next forecast corrected.
- LCR and NSFR calculatorLiquidity coverage and net stable funding built line by line, with encumbrance and six defensible readings.
- Risk-weighted assets (RWA) calculatorStandardised against internal-model RWA, the mortgage loan split, CET1 ratios and the year the output floor binds.
- Credit scorecard modelA points scorecard built from counts: bins, weight of evidence, information value and the leaking variable.
- Price waterfall analysisList price to pocket price for one account and a whole company: nine leakages, ranked and added up.
- Capital call and distribution templateInvestor register, capital call allocation, distribution and the capital account roll, reconciled.
- Value creation bridgeEntry equity to exit equity in six buckets with a zero residual, the cross-term and add-ons net of cash.
- Aircraft lease modelA sale-leaseback priced from the lease rate factor to levered IRR, the residual risk, and the lessor's P&L.
- Ship finance modelA ship loan with LTV covenants and release prices, a bareboat lease with options, a default, and the fund's waterfall.
- Cell tower valuation modelOne tower with one, two and three tenants, a 1,200-tower portfolio, DCF, debt and returns.
- Quality of earnings (QoE) templateReported to diligence-adjusted EBITDA, debt-like items, the NWC peg and the closing statement.
- Bond price, DV01 and duration calculatorPrice, DV01 and modified duration for four Treasuries, roll-down, a DV01-neutral steepener and a hedged client trade.
- LTV and CAC unit economics modelCustomer value by horizon under net revenue retention, the break-even CAC, and the cut test.
- ABS, CLO and RMBS waterfall modelThree securitisations, monthly or quarterly: auto ABS, a CLO under three default paths, and non-QM RMBS.
- Partnership flip tax equity modelA solar partnership flip: ITC and bonuses, the flip year, capital accounts, transfer, recapture and HLBV.
- Battery storage (BESS) financial modelA 200 MW / 800 MWh battery: degradation and augmentation, merchant revenue, three cases, debt and the ITC.
- Population stability index (PSI) calculatorPSI on fixed score bands from development to out of time, and the applicants a model never saw.
- Early payment discount calculator2/10 net 60 as an annual rate, the cash conversion cycle, supply chain finance and a cash pool.
- Discount break-even calculatorVolume needed to break even on a price cut, volume a rise can lose, the rebate cliff and payment terms.
- NAV facility LTV modelEligible NAV, loan to value, a downside, and the second decline that the first ratio hides.
- Reserve-based lending (RBL) modelAn RBL borrowing base from three reserve reports, the bank price deck, hedges and a deficiency cure.
- IPO pricing modelAn IPO from shares and greenshoe to the discount, the book, the first day and a later block.
- Mortgage DTI and underwriting calculatorQualifying income, PITI, housing and debt-to-income ratios, funds to close, the appraisal and FHA and VA files.
- Care home valuation modelA 70-bed care home from admissions and length of stay to EBITDARM, rent cover and value.
- Venture debt modelA two-tranche venture loan with fees and warrants, runway, the realized IRR, a recovery and fund economics.
- Pro rata and dilution calculatorWhat defending ownership through two rounds costs, when it loses money, and whether a 1:1 reserve binds.
- Month-end close and covenant modelClose corrections, ASC 606 allocation, budget variances and the covenant certificate.
- CMBS deal modelA twenty-loan CMBS from the tape to fourteen classes, liquidations, five stresses and surveillance.
- Loan amortization scheduleMonthly schedule for a fixed-rate loan, with extra payments, payoff date and interest saved.
- Rental property calculatorCap rate, cash-on-cash, DSCR and ten-year IRR for one rental bought with a mortgage.
- Fix and flip and BRRRR calculatorOne distressed house run as a flip with hard money and as a BRRRR refinance, with the 70% rule.
- XIRR, NPV and IRR calculatorDated cash flows to XIRR and XNPV, beside IRR and NPV, and the classic NPV() error in numbers.
- 12-month cash flow forecastMonth-by-month cash for a small business: collection timing, supplier timing, buffer and credit line.
- Startup financial model (SaaS)24 months of customers, MRR, burn and runway, the month cash runs out and the round needed.
- Private credit fund modelA levered direct lending fund: income, leverage, losses, fees and an incentive with a hurdle, to net IRR.
- Hotel acquisition modelOccupancy, ADR and RevPAR to GOP, management fees, NOI and a five-year levered IRR.
- Cap table and exit waterfallSAFE, seed and Series A with pool top-ups, then who gets what at five exit values.
- WAULT calculatorWAULT to expiry and to break, by rent and by area, with the rent that can end by year.
- Brinson attribution modelAllocation, selection and interaction by segment, Brinson-Fachler and BHB, reconciled.
- Should-cost modelA supplier quote rebuilt from kilograms, minutes and rates, and the gap split by driver.
- Yield maintenance and defeasance calculatorPrepayment premium on a fixed-rate loan, yield maintenance against defeasance, with a rate grid.
- DPI, TVPI and net IRR templateDPI, TVPI and net IRR on one fund, with and without the NAV, plus PME and a subscription line.
- Evergreen vs drawdown fund calculatorEvergreen net return against a drawdown fund's IRR on committed capital, and where it reverses.
- Family office cost calculatorSingle-family office cost in dollars and basis points, the multi-family fee and the crossover.
- Operational due diligence scorecardODD rating of fund managers on eight domains, and the fatal flaw that averaging approves.
- Co-investment follow-on and reserve modelWhat not following on costs a co-investor, pay-to-play, and the reserve that maximises the multiple.
- KYC remediation capacity modelKYC back book sized in analyst-days, one-year against five-year plans, outreach and exceptions.
- ESG value creation modelESG programme from EBITDA to equity, MOIC and IRR, value protected and the exit multiple.
- AUM and net flow forecast model84 months of gross flows, redemptions, net flows and AUM for a fund sold through platforms.
- Loan pricing and return on capital calculatorTwo loans from margin to net spread and return on capital, the PD at which they tie, floor and prepayment.
- Reinsurance model: quota share to cat XLQuota share and sliding scale, surplus, stop loss, cat XL layers, reinstatements and burning cost.
- Loan workout options modelA defaulted loan's four exits as present values, the indifference price and the provisions.
- Fundraising funnel and timeline modelA first fund raise as a queue: funnel, meetings, committee dates, first close and burn.
- Compound interest and fees calculatorStarting early against late, the cost of a 1% fee, and the result after inflation.
- Debt snowball vs avalanche calculatorFive debts paid off three ways, month by month, and what a starter emergency fund costs.
- European Defence Fund funding rate calculatorEDF blended funding rate, bonuses, partner co-financing, EDIP windows and evaluation scoring.
- Real estate capital stack calculatorValue-add and development capital stacks, DSCR, debt yield, blended cost and leverage math.
- Fund formation modelFund launch budget, fees by close, second-close equalization and the management company P&L.
- Litigation finance modelLitigation funding returns by outcome, the waterfall, a cross-collateralized portfolio and an award buy.
- Industrial development and letting modelA speculative warehouse: monthly carry, weighted letting outcomes, expected margin and land value.
- SRT investor return modelSignificant risk transfer from the investor's side: tranche cash flows, IRR, break-even and stress.
- Development appraisal and cost headroomDevelopment appraisal, the break-even construction cost and the real cost overrun headroom.
- Secondaries discount to NAV calculatorThe real discount on an LP secondary: unsmoothed NAV, unfunded commitment and fees to term.
- Commercial loan and covenant modelA bank's acquisition loan: covenants by quarter through a breach, collateral and return on capital.
- Laundromat acquisition modelLaundromat purchase: SDE, the offer, the SBA injection, the seller note and coverage.
- ASC 842 lease accounting modelASC 842 lessee schedules, entries and classification tests.
- Med spa treatment margin and break-even calculatorMed spa pricing by the unit and the syringe, contribution per room hour and break-even.
- Home care bill rate and break-even calculatorHome care agency pricing: the cost of an aide's hour, the bill rate and the break-even.
- Auto repair shop acquisition modelAuto repair shop purchase: SDE, the offer, the SBA injection, the seller note and coverage.
- purchase price allocation modelASC 805 purchase price allocation, goodwill and impairment.
- Optometry practice revenue per patient and break-even calculatorOptometry practice revenue per patient, the optical's margin and break-even.
- Pharmacy margin per prescription and break-even calculatorIndependent pharmacy economics: the margin per prescription, generic against brand, and the break-even.
This template comes from The Buyout Investor. The book is on Amazon.
If this book helped — or didn’t — a few lines on Amazon are worth more than they look: they are what the next reader goes on. Write a review. The template stays free either way.
Learn to build the whole model
Sixteen video lessons that build a complete LBO model in Excel on one case, from sources and uses to sponsor returns, with step files, exercises that check your answers, a 160-question quiz and the LBO Model, Pro Edition included ($149).