Direct Lending Model Excel Template, Pro Edition
A lender's underwriting model for a sponsor-backed unitranche: lender EBITDA, sizing, OID and exact yield, revolver, sweep and PIK toggle, covenants with headroom and cure, three scenarios, a recovery waterfall and a fair value mark, with 31 built-in checks.
Get this model inside the course: $149 instead of $99
Private Credit Modeling includes the Direct Lending Model, Pro Edition, plus a 32-page Course Book, an Excel workbook that checks your answers and a 160-question quiz with a final exam. For $50 more than the model alone, you learn the whole analysis behind it.
Enter the borrower's last twelve months, the add-backs you accept, the plan and the term sheet. The workbook builds the lender's EBITDA and the sources and uses, runs a six-year loan schedule with no circular reference, tests the covenants, compares Base, Downside and Stress, computes the lender's yields, the recovery in default and the expected loss, and marks the loan at fair value.
Direct Lending Model, Pro Edition: $99
One zip file: the model with a worked example, a blank copy and a 15-page PDF user guide. Single-user license.
Secure checkout by Stripe. Want to learn the whole analysis? Private Credit Modeling, the course, includes this model ($149). The free direct lending model stays free.
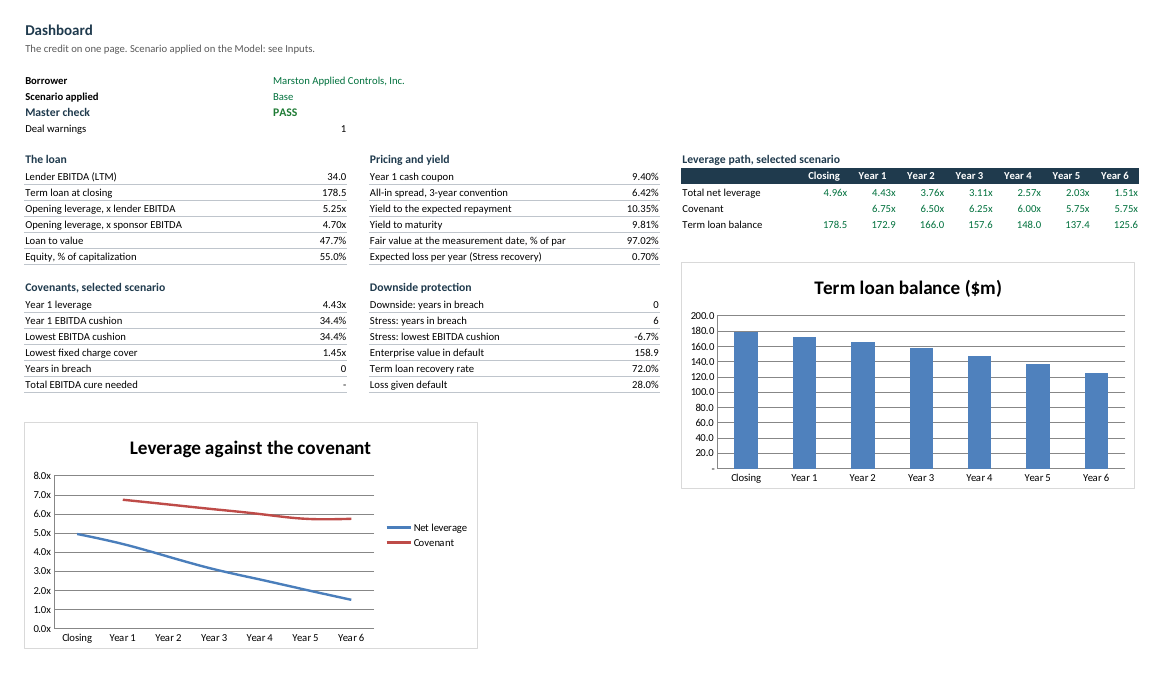
What the model does, tab by tab
Blue text on a pale yellow fill marks an input; every other cell is a formula.
- Dashboard
- Master check and warnings, the loan, pricing and yield, covenants of the selected scenario, downside protection, two charts.
- Inputs
- Borrower, operations and tax, transaction, term loan (OID, fee, margin, floor, amortization, sweep, PIK toggle), revolver, recovery, valuation, four add-backs, the plan by year, three scenarios.
- Transaction
- EBITDA bridge in the sponsor's and the lender's view, enterprise value, loan to value, sources and uses.
- Model
- Six years: operations, rates with the floor, interest on opening balances, tax, CFADS, the cash waterfall with revolver and sweep, balances, credit statistics and covenant tests.
- Covenants
- Total net leverage and fixed charge cover against step-down levels, EBITDA cushion, equity cure needed, years in breach.
- Returns
- Year 1 coupon, the three-year convention, the lender's cash flows and exact yields to the expected repayment (at the call price) and to maturity.
- Scenarios and Engine
- Base, Downside and Stress run in full, side by side, whatever scenario the Model shows.
- Recovery
- Default in the Stress case: distressed value, super senior or pari passu revolver, the waterfall, LGD and expected loss.
- Valuation
- Yield method: calibration at closing, mark at a later date for a change in market yields.
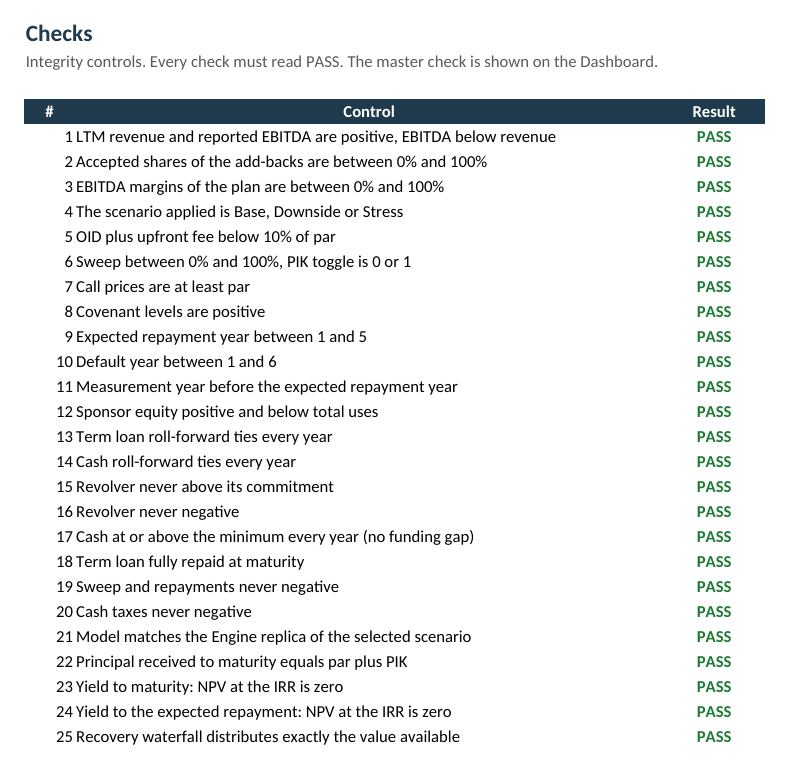
- Checks
- 31 integrity controls, a master check and 6 deal warnings.
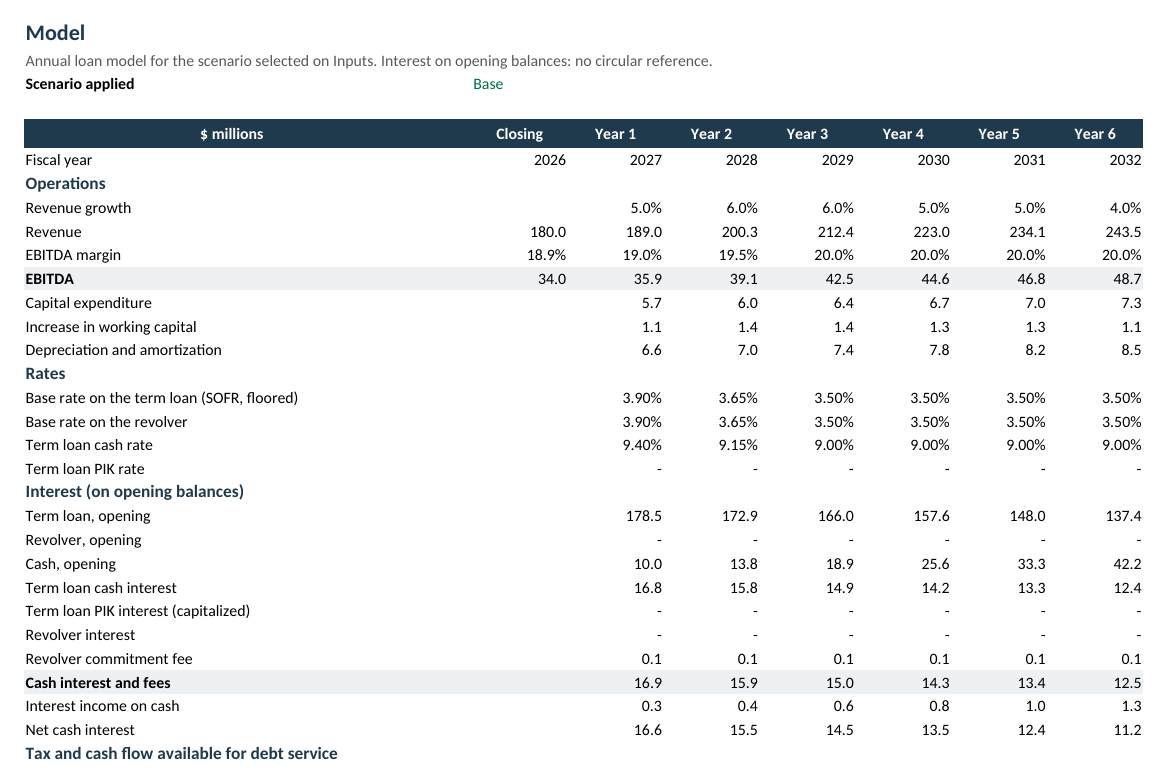
The worked example
Marston Applied Controls, Inc., a fictional US maker of industrial controls, bought by a sponsor at the end of FY2026. Amounts in $ millions:
| Measure | Value |
|---|---|
| Sponsor adjusted / lender EBITDA | 38.0 / 34.0 |
| Enterprise value / unitranche | 374.0 / 178.5 (5.25x) |
| Year 1 coupon / all-in spread (3-year) | 9.40% / 6.42% |
| Yield to year 3 / to maturity | 10.35% / 9.81% |
| Base: year 1 leverage and EBITDA cushion | 4.43x, 34.4% |
| Downside: year 1 leverage and cushion | 5.58x, 17.3% |
| Stress: year 1 leverage, FCCR, cure | 7.20x, 0.90x, 4.13 |
| Recovery in default / LGD / expected loss a year | 72.0% / 28.0% / 0.70% |
| Fair value after 1 year, +50 bps | 97.02% of par |
Technical notes
- Annual periods over six years, amounts in $ millions.
- Standard formulas only: no macros, no data tables, no circular references, no external links, no locked cells.
- Verified against an independent Python model on ten configurations, cell by cell, to one millionth.
- Built for Excel, LibreOffice and Google Sheets.
Questions people ask about it
Does the model use macros or circular references?
No. Interest is charged on opening balances and the revolver is sized before the sweep, so the sheet calculates in one pass: no iterative calculation, no macro, no data table.
How is it different from the free direct lending model?
The free model works one case of The Private Credit Investor with a fixed coupon. The Pro edition is a general tool: EBITDA bridge, SOFR floor, OID and fees with exact yields, revolver, PIK toggle, step-down covenants with cure, three scenarios run side by side, recovery, fair value and 31 checks. The free model stays free.
Does it work in Google Sheets and LibreOffice?
Yes. It uses standard functions only and was recalculated and verified cell by cell in LibreOffice. Charts may look slightly different outside Excel.
What does it leave out?
It is annual, with one term loan and one revolver. There is no delayed draw term loan, no second lien, no first out / last out split, and tax has no loss carry-forward. The guide lists every simplification.
Is there a course that uses it?
Yes: Private Credit Modeling ($149) teaches the whole analysis on the same case and includes this model.
Can I use it on a live deal?
Yes, the blank copy is built for that. The license is single-user, the example borrower is fictional and nothing in the model is investment advice.