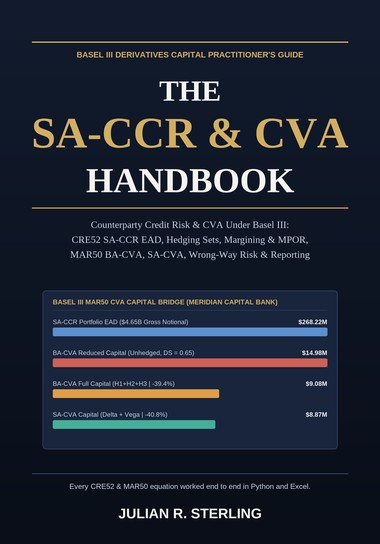
Every Basel III Counterparty Credit Risk (CRE52) and Credit Valuation Adjustment (MAR50) equation worked end to end on a single institutional derivatives portfolio: $4.65B gross notional across five netting sets, five asset classes, unmargined and margined CSAs, 10-day and 20-day MPORs, BA-CVA Reduced, BA-CVA Full, and sensitivity-based SA-CVA.
Built for CCR quant analysts, xVA desks, bank treasury and regulatory capital teams, and model validation engineers implementing US 12 CFR 217.132, EU CRR3 (Articles 274-280f and 381-386), and UK PRA Basel 3.1.
Free companion Excel calculator
Download the live, formula-driven SA-CCR EAD and MAR50 CVA Capital workbook pre-loaded with Meridian Capital Bank N.A.'s complete multi-asset portfolio, dynamic Controls tab, and side-by-side BA-CVA vs. SA-CVA bridge.
Open the free SA-CCR & CVA Excel Calculator →Worked Case Summary: Meridian Capital Bank N.A.
| Metric | Value | Basel Reference |
|---|---|---|
| Total Derivatives Gross Notional | $4,650.00M | 5 Netting Sets, 20 Trades |
| Total Replacement Cost (RC) | $35.40M | CRE52.10-CRE52.18 |
| Total Potential Future Exposure (PFE) | $156.19M | CRE52.20-CRE52.72 |
| Total SA-CCR EAD (alpha = 1.4) | $268.22M | CRE52.1 |
| Counterparty Credit Risk RWA | $206.31M | Standardized Credit RW |
| BA-CVA Reduced Capital (DS = 0.65) | $14.98M | MAR50.14 (RWA $187.25M) |
| BA-CVA Full Capital (H1+H2+H3) | $9.08M | MAR50.21 (-39.4% relief) |
| SA-CVA Capital (Delta + Vega, m = 1.0) | $8.87M | MAR50.27 (-40.8% vs. Reduced) |