Book · Julian R. Sterling
The Basel III Output Floor Handbook
The 72.5% Output Floor and Revised Standardized Approach to Credit Risk (CRE20): Transitional Phase-In 2025-2030, SCRA vs ECRA for Banks, LTV Real Estate Risk Weights, Unrated Corporates, IRB vs SA Capital Impact, and EU CRR3 vs UK PRA
About the book
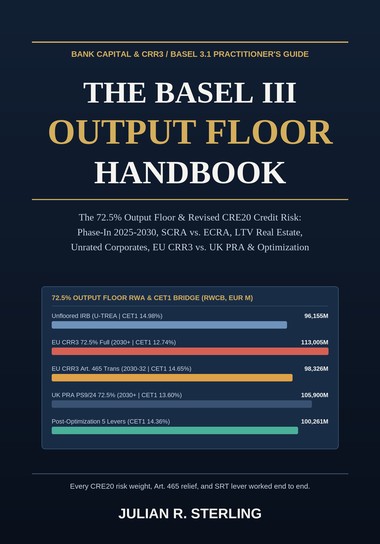
Under BCBS RBC20.11-20.14, EU CRR3 (Regulation (EU) 2024/1623, effective 1 January 2025), and UK PRA PS9/24 (effective 1 January 2027), IRB banks can no longer allow aggregate Risk-Weighted Assets to fall below 72.5% of the Revised Standardized Approach (CRE20, FRTB-SA, SA-CCR, SEC-SA, and SMA). Once the floor binds, marginal capital consumption flips from internal models to 72.5% of S-TREA, reshaping pricing and ROE across unrated corporate lending, prime mortgages, and undrawn credit lines.
One complete European IRB bank carries every calculation from exposure line to Board capital plan. On Rheinland-West Commercial Bank AG (RWCB, EUR 14,400.00M CET1, EUR 96,155.00M U-TREA vs. EUR 155,868.28M fully loaded S-TREA), the 72.5% output floor adds EUR 16,849.50M (+17.52%) to Total RWA (EUR 113,004.50M), cutting CET1 from 14.98% to 12.74% (-224 bp). EU CRR3 Article 465 reliefs save EUR 20,246.22M of S-TREA through 2032 (keeping CET1 at 14.65%), before creating a EUR 14,678.51M (-191 bp) cliff edge on 1 January 2033. Executing five structural optimization levers strips EUR 17,574.57M from S-TREA and restores fully loaded CET1 to 14.36% (+162 bp).
What is inside:
- 15 chapters in four parts covering BCBS RBC20, CRE20, CRE30-32, EU CRR3 (Reg. 2024/1623), UK PRA PS9/24, and US Collins Floor comparisons
- Complete worked exposure-level IRB-to-SA bridge across Sovereigns, Banks (ECRA vs. SCRA Grades A Enhanced, A, B, C & sovereign floor), Corporates, SMEs, Specialized Lending, RRE, CRE/IPCRE/ADC, Retail Transactors, and Off-Balance-Sheet CCFs
- Exact algebraic comparison of EU CRR3 Art. 125 & UK PRA Loan-Splitting vs. BCBS CRE20.82 Whole-Loan LTV risk weights and Art. 465(5) low-risk residential relief
- Non-credit standardized floors (FRTB-SA, SA-CCR, SA-CVA, SEC-SA for synthetic SRTs, and Operational Risk SMA as a natural floor donor)
- Portfolio-level Floor Contribution attribution, MDA/P2R/P2G stack dynamics, dual-metric RAROC repricing, five quantified optimization levers, and Pillar 3 CMS1/CMS2 governance
Free: the Basel III Output Floor & CRE20 RWA Calculator in Excel
Computes U-TREA vs. S-TREA across 29 exposure lines, EU CRR3 2025-2033 phase-in (with and without Article 465 reliefs), UK PRA PS9/24 2027-2030 trajectory, interactive RRE LTV and SCRA/ECRA calculators, and five optimization levers. Pre-loaded with RWCB, 100% live formulas, dynamic Controls tab, no macros, nothing locked.
Contents
- Chapter 1: The Basel III Output Floor Formula (RBC20.11-20.14) and Scope of Application
- Chapter 2: Transitional Phase-In Schedules (2025-2030) and the Capital Cliff
- Chapter 3: IRB Reforms, Input Floors, and the New IRB-to-SA Bridge
- Chapter 4: Sovereign, PSE, and Multilateral Development Bank Exposures
- Chapter 5: Bank Exposures: ECRA vs. SCRA (Grades A, B, C) and the Sovereign Floor
- Chapter 6: Rated Corporates, Unrated Corporates, SMEs, and Specialized Lending
- Chapter 7: Residential Real Estate (RRE): Whole-Loan LTV Bands vs. Loan-Splitting
- Chapter 8: Commercial Real Estate (CRE), IPCRE, and ADC Exposures
- Chapter 9: Retail Portfolios (Transactors vs. Non-Transactors) and Off-Balance-Sheet CCFs
- Chapter 10: Non-Credit Standardized Floors: FRTB-SA, SA-CCR, SA-CVA, SEC-SA, and SMA
- Chapter 11: EU CRR3 Article 465 Transitional Reliefs (2025-2032) and the 2033 Cliff Edge
- Chapter 12: UK PRA PS9/24 vs. EU CRR3 vs. US Endgame: Comparative Capital Impact
- Chapter 13: Portfolio-Level RWA Attribution and CET1 / MDA Buffer Erosion
- Chapter 14: Five Capital Optimization Levers Under a Binding Output Floor
- Chapter 15: Data Architecture, Dual-Calculation Governance, and Pillar 3 Disclosures
- Conclusion & Appendices A, B, and C (Complete RWCB Schedules, Checklists, Glossary)
Read first
To read: Basel III 72.5% Output Floor Formula, Break-Even Multiplier, and 2025-2030 Phase-In
To read: CRE20 SCRA vs. ECRA for Bank Exposures: Grades A, B, C, and Sovereign Floor
To read: EU CRR3 Article 465 Output Floor Transitional Reliefs (2025-2032) and the 2033 Cliff
Updates
Regulatory standards are stated as of November 2026, reflecting BCBS RBC20 and CRE20 (BCBS 424), EU CRR3 (Regulation (EU) 2024/1623, effective 1 January 2025), and UK PRA PS9/24 and PS17/23 (effective 1 January 2027, full 72.5% end-state 1 January 2030). Any future EBA Article 518c review or PRA updates will be posted here.
Also by Julian R. Sterling
Related banking, capital, and risk management handbooks. The full list is on the author page.