Book · Julian R. Sterling
The Basel III Leverage Ratio Handbook
Tier 1 Leverage Exposure and Buffer Mechanics Under Basel III: LEV30 Total Exposure Measure, Derivatives SA-CCR Add-Ons, SFT Netting, Off-Balance-Sheet CCFs, G-SIB Leverage Buffer, US SLR and eSLR, and EU CRR2
About the book
The Basel III leverage ratio was designed as a simple, non-risk-based backstop to risk-weighted capital. In practice, for global dealers, clearing banks, and low-RWA-density balance sheets, LEV30 and LEV40 often operate as the binding capital constraint governing repo desks, derivative portfolios, Treasury intermediation, and dividend capacity.
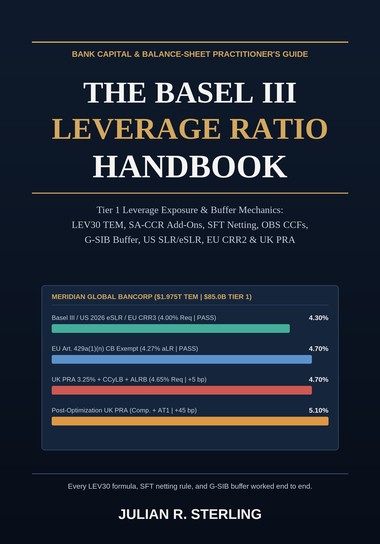
One complete G-SIB balance sheet carries every calculation from published accounting assets to cross-border regulatory compliance. In Meridian Global Bancorp ($85,000.00M Tier 1 capital, $550,000.00M RWA, $1,684,300.00M total accounting assets), the LEV30 Total Exposure Measure reaches $1,975,000.00M, producing a baseline Basel III leverage ratio of 4.30%. That clears the 4.00% Basel III, EU CRR3, and US recalibrated eSLR requirement (finalized November 2025, effective April 1, 2026; evaluated on MGB's Basel TEM spot proxy) by +30 bp (+$6,000.00M), breaches the legacy US 5.00% BHC eSLR by -70 bp, and sits just +5 bp (+$835.00M) above the UK PRA 4.65% combined leverage requirement (at 4.70% ex-reserves), making UK PRA MGB's tightest active binding envelope. Executing $85,000.00M of repo, derivative, and commitment compression plus $3,000.00M of AT1 issuance lifts Basel III leverage to 4.66% and widens UK PRA headroom to +45 bp (+$7,787.50M) at 5.10%.
What is inside:
- 15 chapters in four parts covering BCBS LEV10 to LEV40 (BCBS 270, BCBS 424, BCBS 467, BCBS 468), US 12 CFR 217.10 (including the November 2025 recalibrated eSLR final rule effective April 1, 2026), EU CRR2 and CRR3 Articles 429 to 429g, CRD V Article 141b, and the UK PRA Rulebook (including PS22/25 effective January 1, 2026)
- Modified SA-CCR derivative mechanics: Replacement Cost with the 5 cash variation margin criteria (LEV30.25), PFE multiplier locked at 1.00 (LEV30.20), QCCP client-clearing IM relief, and written credit derivative effective notional offsets
- Securities Financing Transactions (SFTs): strict LEV30.37(1) cash leg netting, MNA vs. transaction-by-transaction E* counterparty credit risk add-on, and agency SFT indemnity rules
- Finalized Basel III off-balance-sheet CCFs (10%, 20%, 40%, 50%, 100%) contrasted against legacy BCBS 270 maturity splits
- G-SIB leverage ratio buffer (50% of RWA surcharge), 4-quartile L-MDA distribution restrictions, EU Art. 429a(1)(n) central bank reserve exemption with upward aLR recalibration, and UK PRA 3.25% + 35% CCyLB + 35% ALRB mechanics
- Repo compression and FICC sponsored clearing, multilateral OTC trade compression, leverage ratio stress testing, FTP leverage pricing (45.33 bp Basel / 52.70 bp UK PRA), DIS80 LR1/LR2 disclosures, and quarter-end window-dressing controls
Free: the Basel III Leverage Ratio & SLR Calculator in Excel
Computes the full LEV30 Total Exposure Measure (On-BS, Modified SA-CCR Derivatives, Written CDS, SFT Netting & E* Add-On, OBS CCFs), LR1 accounting bridge, cross-jurisdictional pass/breach matrix (Basel III, US 2026 eSLR, EU aLR, UK PRA), optimization, stress test with L-MDA quartiles, and FTP leverage charge. Pre-loaded with Meridian Global Bancorp, 100% live formulas, zero macros.
Contents
- Chapter 1: Origins and Regulatory Architecture of the Basel III Leverage Ratio
- Chapter 2: The Tier 1 Capital Numerator, Regulatory Deductions, and Capital Quality Constraints
- Chapter 3: On-Balance-Sheet Exposures, Accounting Consolidation, and Settlement-Date Mechanics
- Chapter 4: Derivative Exposures Under Modified SA-CCR: RC, Cash VM, and the PFE Multiplier
- Chapter 5: Client-Cleared QCCP Derivatives and Written Credit Derivatives
- Chapter 6: Securities Financing Transactions (SFTs): Cash Leg Netting and Balance-Sheet Mechanics
- Chapter 7: SFT Counterparty Credit Risk Add-On (E*), Master Netting Agreements, and Agency SFTs
- Chapter 8: Off-Balance-Sheet Exposures and Basel III Finalization Credit Conversion Factors
- Chapter 9: The G-SIB Leverage Ratio Buffer, L-MDA Distribution Restrictions, and Pillar 2 Add-Ons
- Chapter 10: United States SLR and eSLR: 12 CFR 217.10, Daily Averaging, Custody Relief, and April 2026 Recalibration
- Chapter 11: European Union CRR2 and CRR3 (Articles 429 to 429g) and Central Bank Reserve Exemptions
- Chapter 12: United Kingdom PRA Leverage Ratio Framework: 3.25% Minimum, Permanent Reserve Exclusion, CCyLB, and ALRB
- Chapter 13: Balance-Sheet Optimization: Repo Compression, Sponsored Clearing, Trade Compression, and Commitment Pruning
- Chapter 14: Leverage Ratio Stress Testing, RWA-vs-Leverage Binding Constraints, and Funds Transfer Pricing (FTP)
- Chapter 15: Regulatory Reporting, Pillar 3 Disclosures (LR1/LR2), Window-Dressing Controls, and ALCO Governance
- Conclusion & Appendices A, B, and C (Full MGB Schedules, Netting & Audit Checklists, Glossary)
Read first
To read: Basel III Leverage Ratio Total Exposure Measure (LEV30): Formula and Worked Example
To read: Leverage Ratio SFT Netting and Counterparty Credit Risk Add-On (E*) Under LEV30
To read: US SLR and April 2026 eSLR vs. EU CRR2/CRR3 and UK PRA Leverage Ratio Rules
Updates
Regulatory standards are stated as of November 2026, reflecting BCBS LEV10 to LEV40 and DIS80, the November 2025 Fed/OCC/FDIC eSLR final rule (effective April 1, 2026), EU CRR2 and CRR3 Articles 429 to 429g, CRD V Article 141b, and the UK PRA Rulebook (including PS22/25 effective January 1, 2026). Any future revisions will be posted here.
Also by Julian R. Sterling
Related banking, treasury, and capital management handbooks. The full list is on the author page.